
Atlanta, Georgia
Buckhead
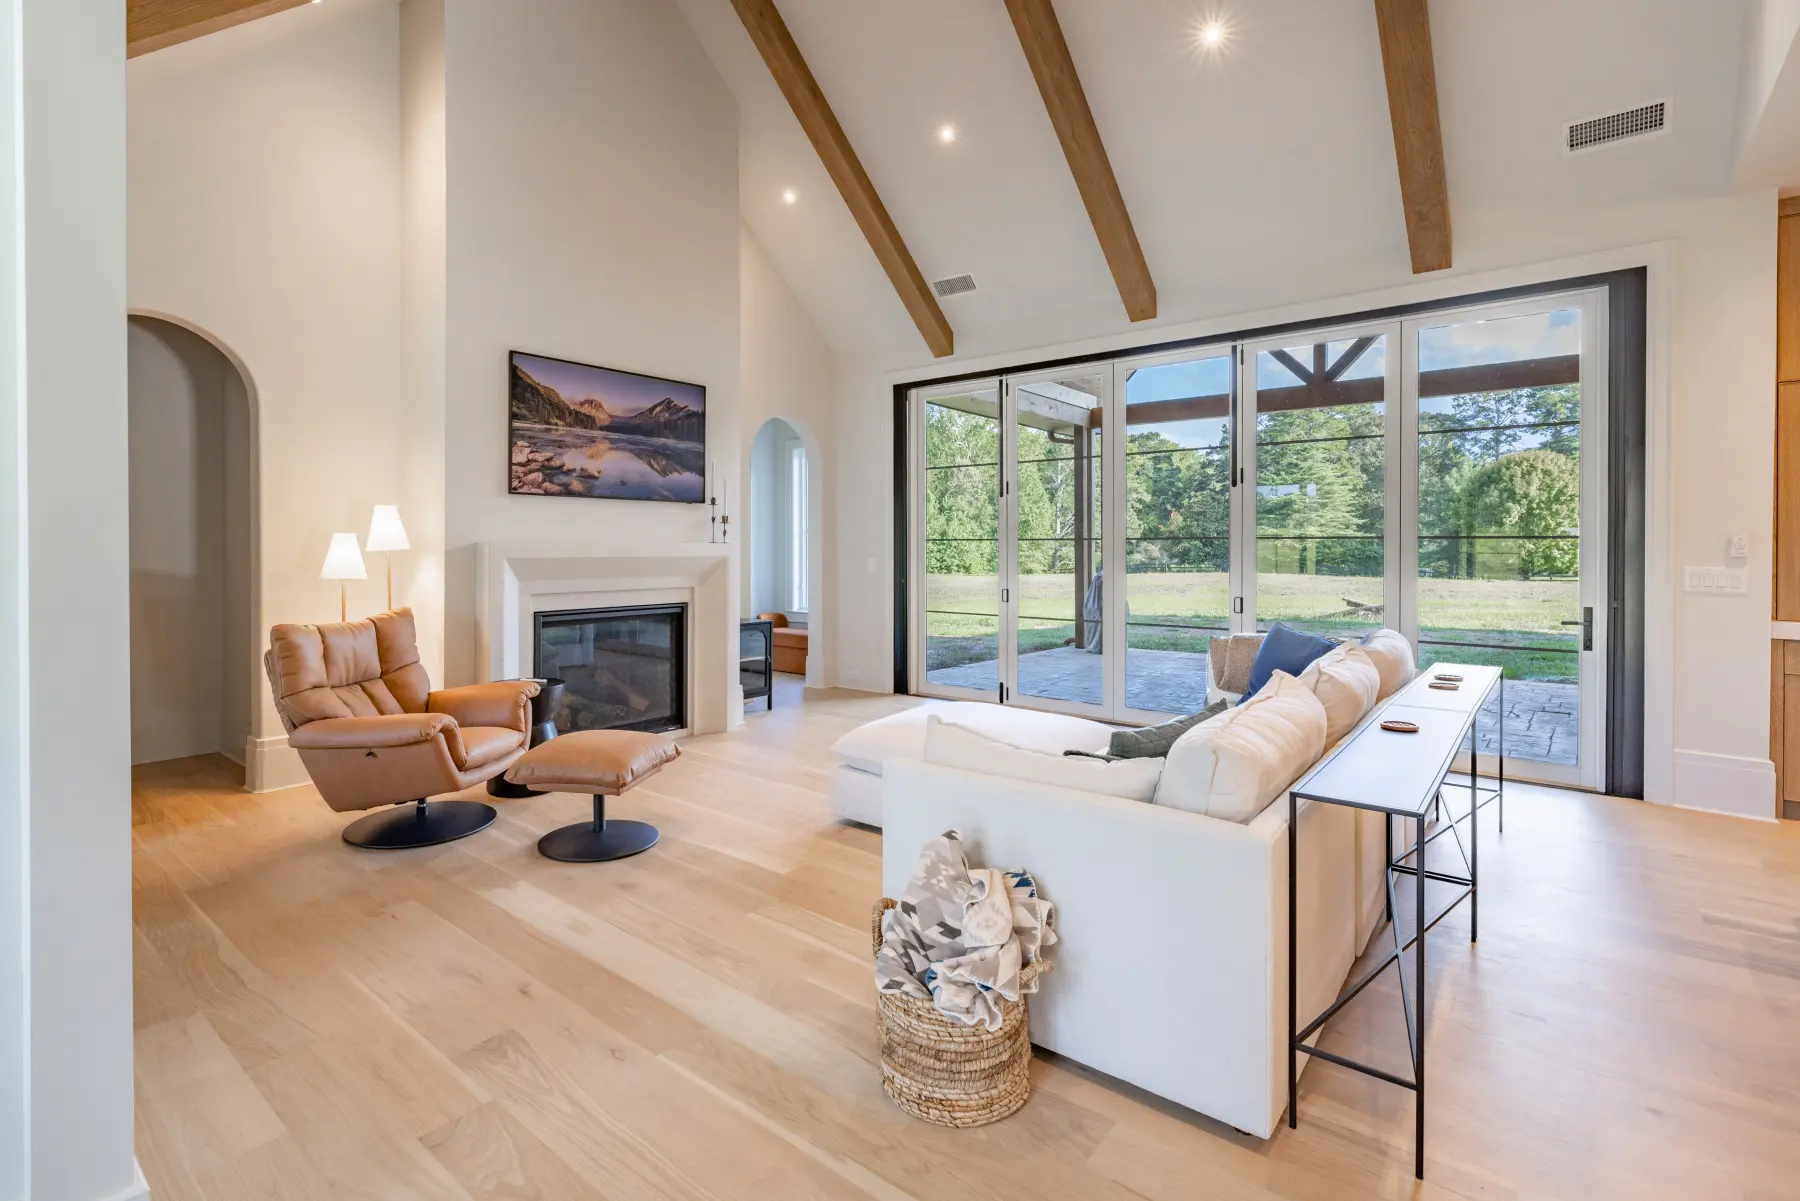
Atlanta’s premier residential address, where our team has built since 2017.
KAIYA Growth Fund · Tax-free growth
You own shares in Kaiya’s operating company, the business that buys the land and builds every home in Buckhead and Newport Beach. Because it is an active, growing business, your shares are structured for Qualified Small Business Stock (QSBS), so gains on shares held five years are excluded from federal capital gains tax.
A summary of the offering. Complete terms are set out in the offering documents.
You own part of the company behind every Kaiya home. It buys the land, builds the homes and sells them, and keeps your capital working for five years. Then you are paid first, and your gains can be free of federal capital gains tax.
01
You receive newly issued shares in Kaiya’s operating company, the business that runs every project from land to sale.
02
The fund buys sites in Buckhead and Newport Beach, and Goodwin Luxury Homes, our in-house builder, develops each home with construction financing up to 90% of cost.
03
Profits from home sales are redeployed into new projects. There are no distributions during the first five years.
04
After five years, investors receive their capital plus a 24% annual preferred return before Kaiya earns anything, with gains on qualifying shares excluded from federal capital gains tax.

Qualified Small Business Stock
Under Section 1202 of the tax code, gains on qualified small business stock held for five years or more are excluded from federal capital gains tax.
QSBS applies to shares in active operating companies, not passive real estate holdings. Owning part of the company that builds the homes is what makes the tax benefit possible.
No distributions before year five keeps your capital invested for the full period the exclusion requires.
The fund keeps building. Sale proceeds are redeployed into new projects rather than winding the fund down.
Alignment
The fund charges investors no fees. Investors receive their capital and a 24% annual preferred return before Kaiya earns anything, and Kaiya takes the first loss if a project falls short.
Kaiya does well only when the homes it builds sell well, and only after investors have been paid.
An investment that reaches the fund’s 3.03x target, and the federal capital gains tax the QSBS exclusion removes from the gain.
| Investment | Value at 3.03x | Gain | Federal tax avoided |
|---|---|---|---|
| $100,000 | $303,000 | $203,000 | $48,314 |
| $250,000 | $757,500 | $507,500 | $120,785 |
| $500,000 | $1,515,000 | $1,015,000 | $241,570 |
| $1,000,000 | $3,030,000 | $2,030,000 | $483,140 |
For illustration only. Assumes the 3.03x target is reached on shares held five years or more, and a 23.8% federal rate on long-term gains (20% plus the 3.8% net investment income tax). Targets are not guaranteed.
Both markets have mature neighborhoods, little land left to develop and steady demand from high-net-worth buyers.
Atlanta, Georgia
Atlanta’s premier residential address, where our team has built since 2017.

Southern California
A coastal market with limited inventory and long-standing demand for new luxury homes.
Vertically integrated
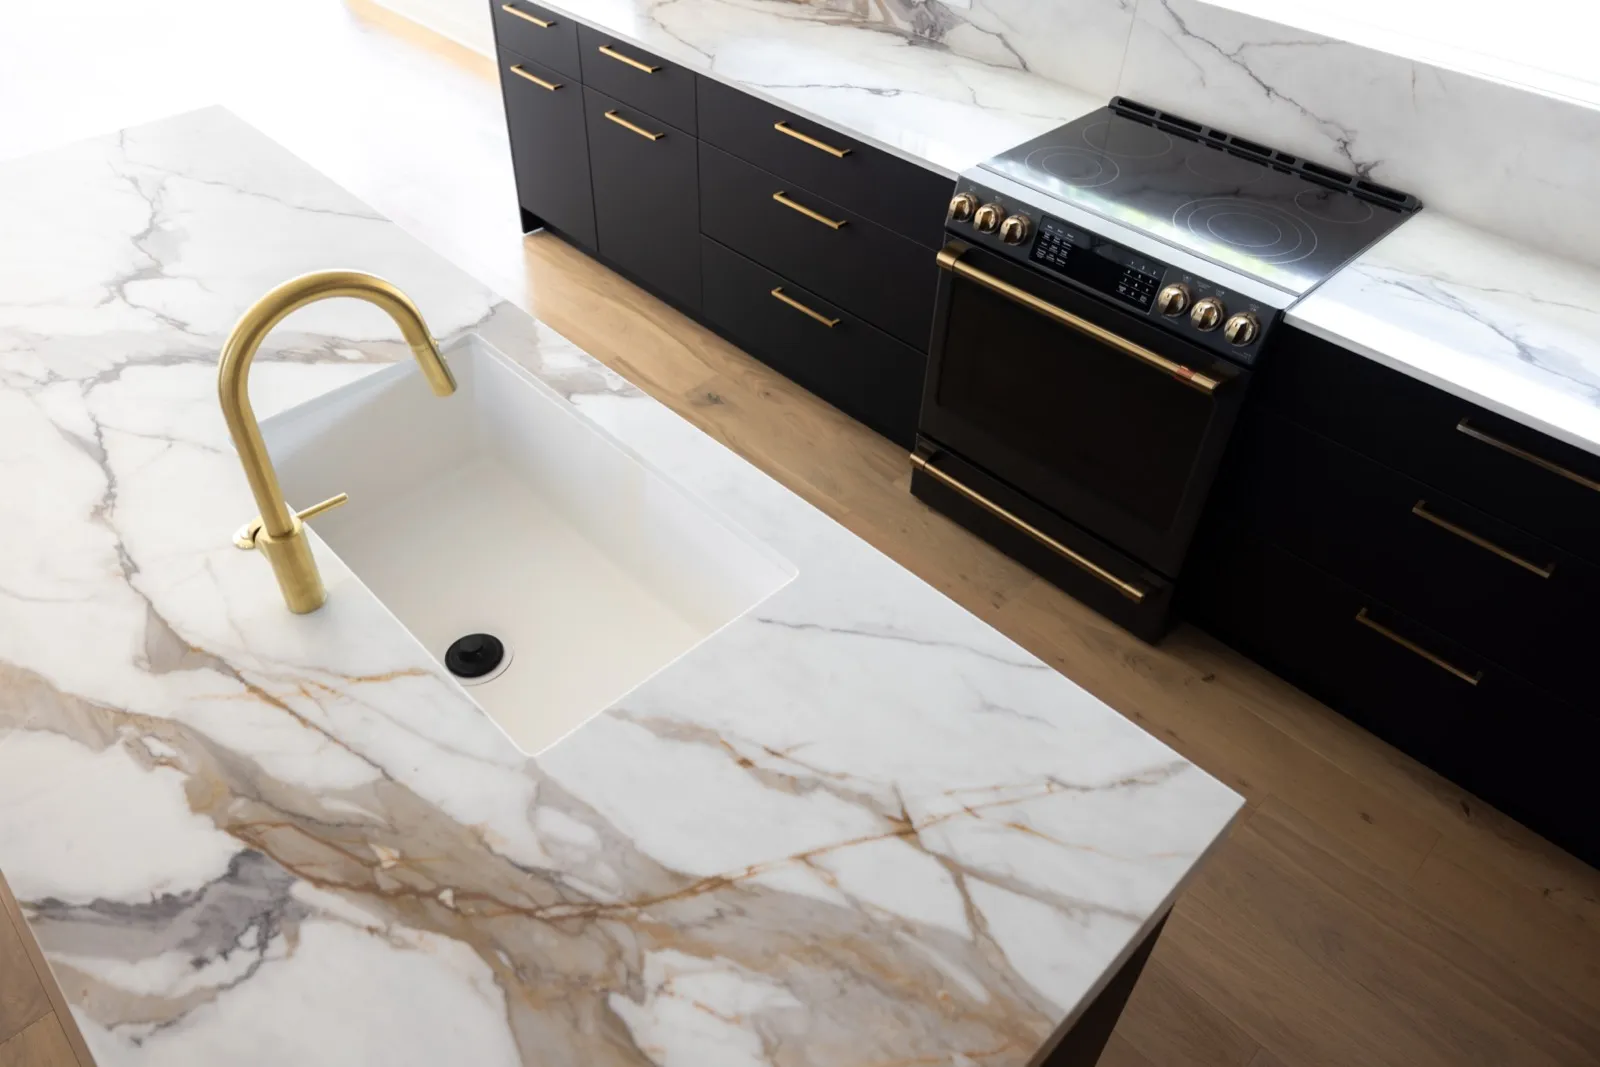
Kaiya acquired Goodwin Luxury Homes, an architecture-led design-build firm, so that every fund project is designed and built in-house. There is no outside general contractor between the fund and the finished home.
01
Tell us about yourself and we will send the offering documents.
02
The fund is open to accredited investors only, and accreditation is confirmed before investing.
03
Complete the subscription documents and fund your investment. Your shares are issued directly by Kaiya’s operating company.
04
Follow the fund’s progress in the investor portal while your capital works toward the five-year mark.
Qualified Small Business Stock, defined in Section 1202 of the tax code. When shares in a qualifying C-corporation are bought directly from the company and held for at least five years, the gain on those shares can be excluded from federal capital gains tax.
Newly issued shares in Kaiya’s operating company: the business that acquires the land and builds and sells every home, through its in-house builder, Goodwin Luxury Homes. Your returns come from the profit on the homes it sells.
Because that is what makes the tax benefit possible. QSBS applies to shares in active businesses, not passive real estate holdings. The company still holds real assets, land and homes under construction, and investors keep the same protections: they are paid first, and Kaiya takes the first loss.
Investors earn a 24% preferred return per year on their invested capital. It is simple, not compounded, and it is paid to investors before Kaiya earns any profit.
There are no distributions during the first five years. After that, investors are paid first: their capital plus the 24% annual preferred return, ahead of Kaiya.
The full QSBS exclusion applies to shares held for five years or more. Keeping capital invested for that period lets the fund keep building and lets investors qualify for the exclusion.
Yes. Each project uses construction financing of up to 90% of its cost, which is what allows the equity in the fund to target a 3.03x multiple.
Kaiya takes the first loss. Losses are absorbed by Kaiya before they reach investors.
No. The fund charges investors no fees. Kaiya earns only what remains after investors are paid.
The KAIYA Fund is a debt investment that pays a fixed 10% a year in monthly interest. The Growth Fund is an equity investment with no distributions for five years, designed for long-term growth and tax-free gains.
Accredited investors only, including individuals, joint accounts, trusts, entities and family offices.
No. 3.03x is a target, and all investments carry risk, including the possible loss of principal. Please review the risk factors in the offering documents.
We will walk you through the KAIYA Growth Fund, the current projects and how to get started.
The KAIYA Growth Fund is offered only to accredited investors, and only through its offering documents. This page is a summary and does not describe every term or risk. All investments involve risk, including the loss of principal. The 3.03x multiple and 24% preferred return are targets and are not guaranteed. Tax outcomes depend on each investor’s circumstances; investors should consult their own tax advisors. Past performance is not indicative of future results.